Merchant credit risk frameworks
Segmentation, probability of default (PD) matrices, exposure calculations and collateral triggers (rolling reserves, holdbacks, settlement delays) for acquirers and payment providers.
Practical credit risk, collections and analytics for payments and lending businesses: complex maths, explained in plain English.
Discuss a projectSegmentation, probability of default (PD) matrices, exposure calculations and collateral triggers (rolling reserves, holdbacks, settlement delays) for acquirers and payment providers.
Expected credit loss (ECL) models your auditors can follow, built on your own processing data.
See the true margin of each merchant or customer once credit losses are factored in.
Segmentation, payment-method optimisation and performance analysis that cut arrears and cost.
Monthly scoring and provisioning reports, so your team doesn't have to run them.
We agree the methodology, policies and assumptions with your Risk and Finance teams.
We build the calculators and data pipeline, run your live portfolio and hand over with training.
Optional monthly batch runs and reporting.
Fixed-fee, phased projects. You sign off each stage before the next begins.
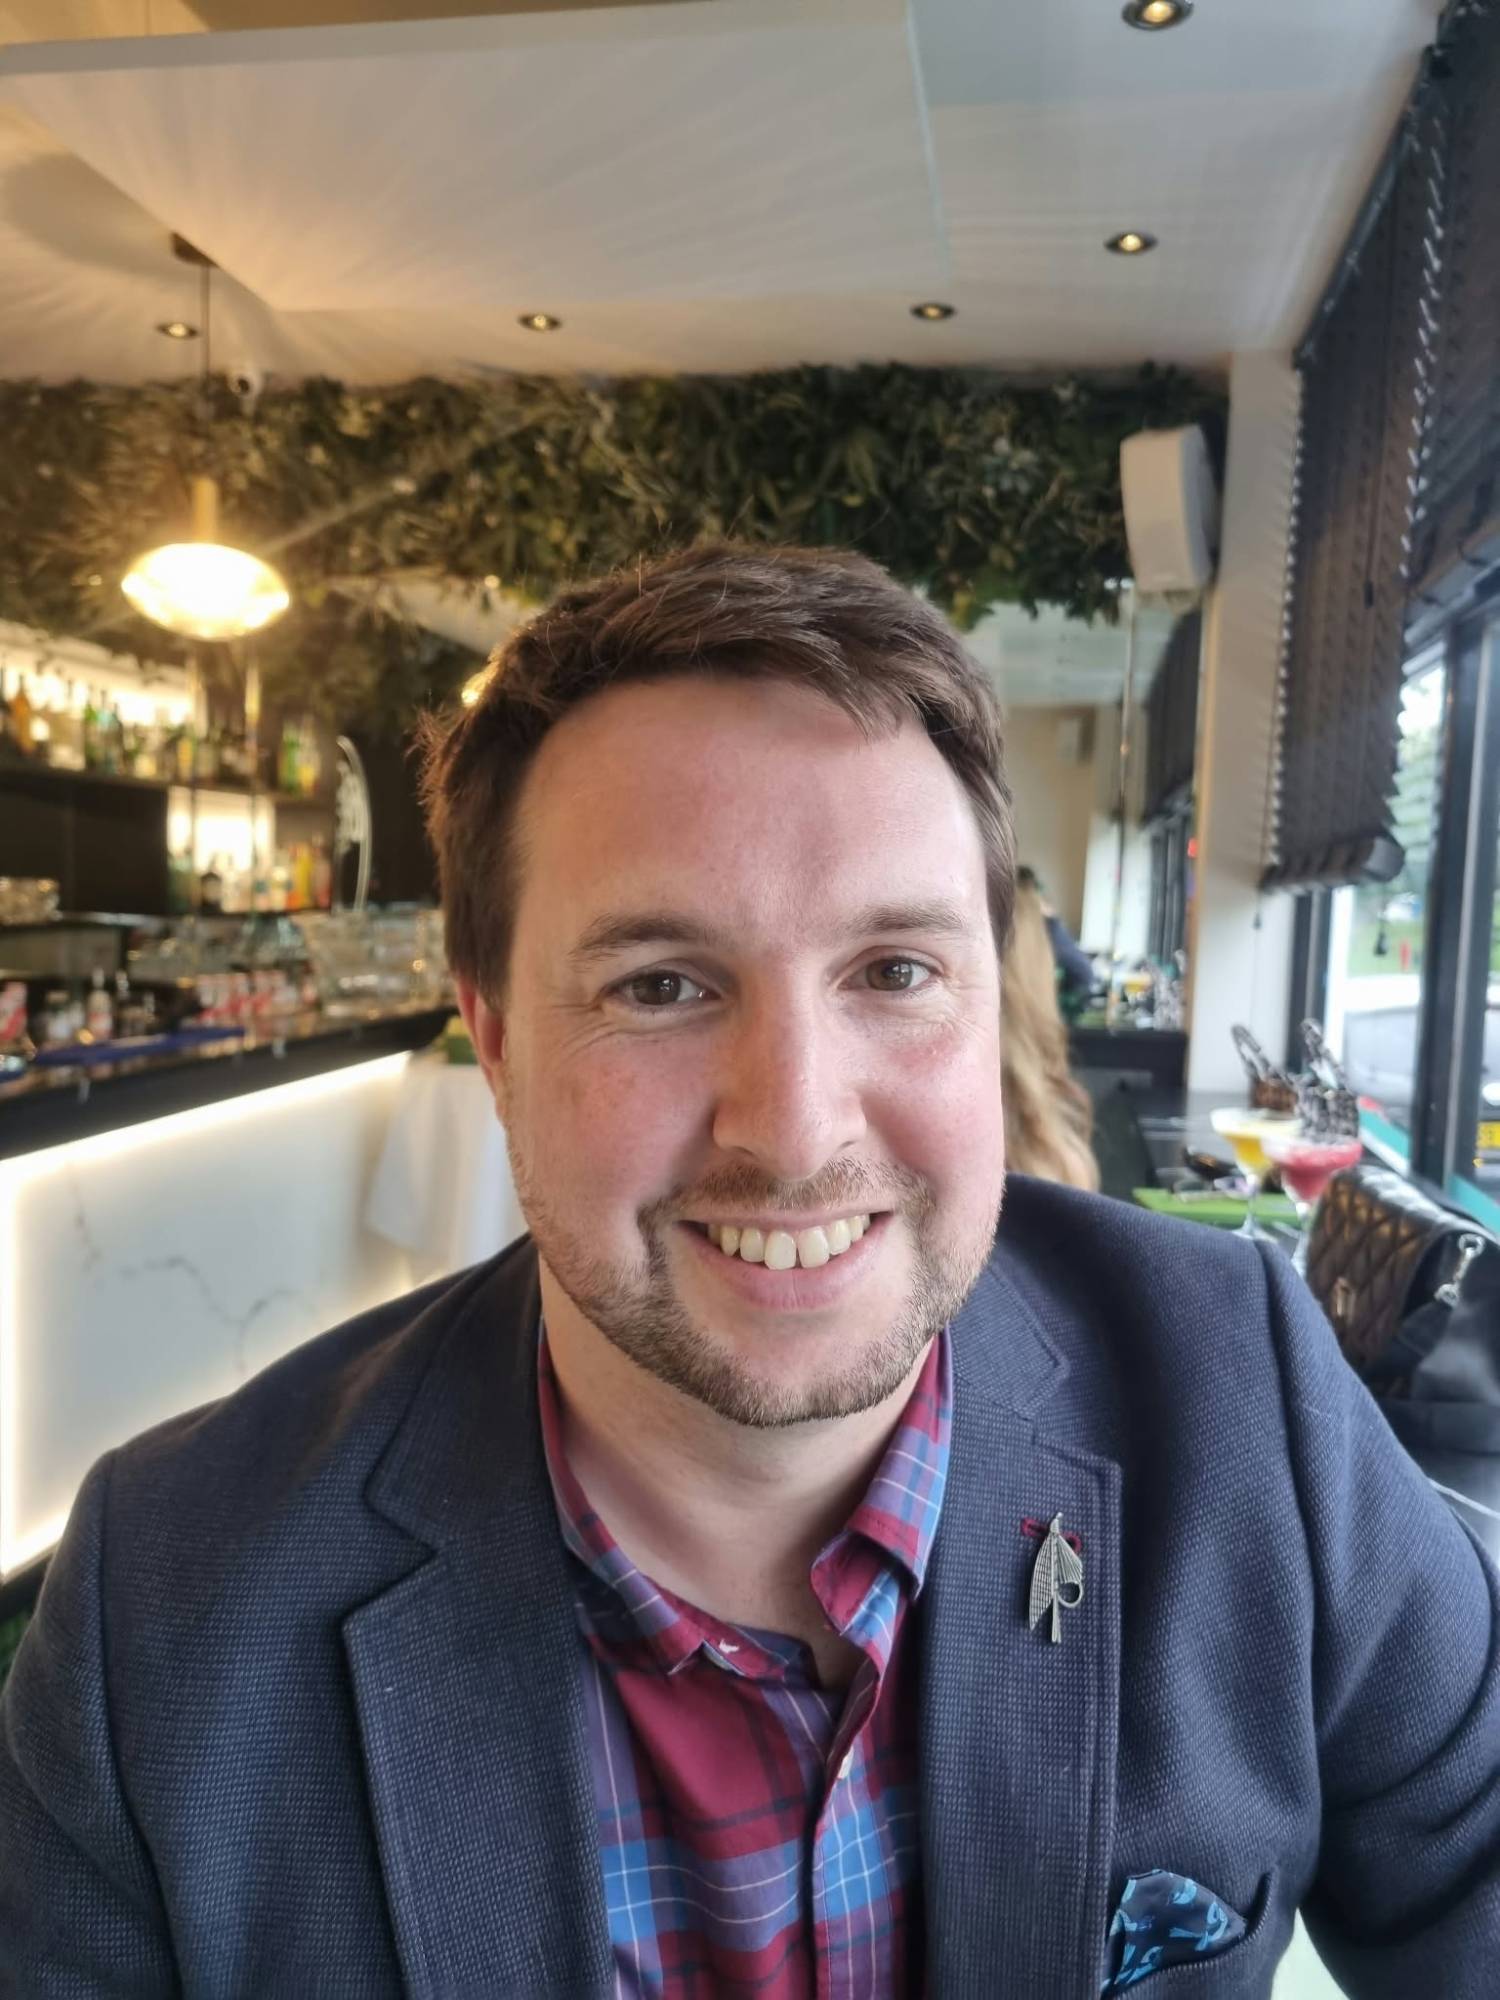
Mathen Analytics is led by Daniel Sattary, a credit risk and collections leader with 15+ years across UK lenders, payments and pan-European collections. He has:
He also holds an MMath from the University of Sussex.